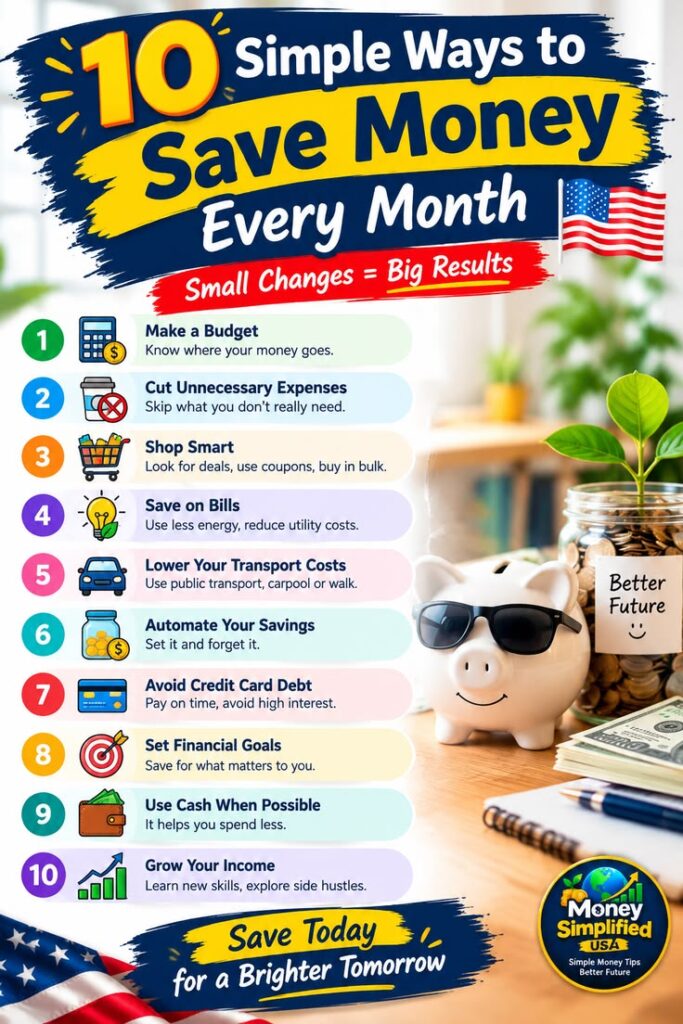
Saving money is one of the most important steps toward achieving financial stability. Whether you are a student, a salary earner, a business owner, or a freelancer, learning how to save can help you prepare for emergencies, achieve your financial goals, and reduce money-related stress.
However, saving money is not always easy. Rising living costs, unexpected expenses, family responsibilities, and daily spending can make it difficult to set money aside. Sometimes, you may earn money with the intention of saving, only to discover that nothing is left at the end of the month.
The good news is that you do not need to earn a huge income to start saving. With the right habits and a practical plan, you can gradually build your savings, even when your income is limited.
In this article, we will explore ten simple ways to save money every month and improve your financial life.
1. Create a Monthly Budget
One of the easiest ways to save money is to create a monthly budget. A budget helps you understand how much money you earn, how much you spend, and how much you can afford to save.
Without a budget, it is easy to spend money on unnecessary things without realizing how quickly your income is disappearing.
Start by writing down your total monthly income. Next, list your essential expenses, such as food, transportation, rent, electricity, school fees, and other bills. Then, identify how much money you can comfortably set aside for savings.
For example, if you earn ₦150,000 monthly, you could create a budget that covers essential expenses, personal needs, savings, and unexpected costs.
Your budget should reflect your actual financial situation rather than an unrealistic spending plan. Review it regularly and make adjustments when necessary.
2. Pay Yourself First
Many people wait until the end of the month before saving money. Unfortunately, this approach often fails because other expenses consume the money first.
A better strategy is to pay yourself first. This means setting aside a portion of your income for savings as soon as you receive it.
For example, if you receive your salary on the 25th of every month, transfer your planned savings into a separate account immediately after payment.
You do not have to start with a large amount. Even saving ₦2,000, ₦5,000, or ₦10,000 consistently can help you develop a strong savings habit.
The important thing is to choose an amount you can maintain without neglecting essential expenses.
3. Track Your Daily Expenses
Small purchases can have a significant impact on your finances when they happen repeatedly. Buying snacks, ordering food, making unnecessary transfers, or taking expensive transportation options may seem harmless individually, but these expenses can add up.
Tracking your expenses helps you identify where your money goes.
You can use a notebook, a spreadsheet, or a budgeting application to record your daily spending. At the end of each week, review your expenses and identify areas where you can cut back.
For example, spending ₦1,000 unnecessarily every day adds up to approximately ₦30,000 over 30 days.
Once you understand your spending habits, you can make better decisions about how to use your money.
4. Reduce Impulse Buying
Impulse buying happens when you purchase something without planning for it. This often occurs when you see attractive products online, encounter discounts, or shop while emotional.
Although buying something new can feel exciting, repeated impulse purchases can prevent you from reaching your savings goals.
Before buying a non-essential item, give yourself 24 to 48 hours to decide whether you genuinely need it.
You can also create a shopping list before visiting a market or supermarket and commit to purchasing only the items on that list.
Another useful strategy is to unsubscribe from promotional messages that encourage unnecessary spending.
Remember that a discount does not automatically mean you are saving money. If you purchase something you do not need, you are still spending money.
5. Cook More Meals at Home
Food is a major expense for many households. While eating at restaurants or ordering meals can be convenient, doing so frequently may consume a large part of your monthly income.
Preparing more meals at home can help you reduce these costs.
Plan your meals for the week, prepare a shopping list, and buy ingredients according to your needs. Where practical, purchase frequently used non-perishable items in larger quantities if the total cost is lower and you can store them properly.
You can also prepare meals in advance to reduce the temptation to order food when you are tired or busy.
This does not mean you must stop eating out completely. Instead, set a reasonable budget for eating out and try to stay within it.
With consistent meal planning, you may discover that you can eat well while spending less.
6. Set Clear Savings Goals
Saving money becomes easier when you have a specific reason for doing it.
Instead of simply saying, “I want to save money,” identify what you are saving toward. Your goal could be building an emergency fund, paying school fees, buying a laptop, starting a business, or preparing for future expenses.
Give each goal a target amount and a deadline.
For example, if you want to save ₦60,000 in six months, you would need to save ₦10,000 monthly, assuming you make no withdrawals and earn no interest.
Breaking a large target into smaller monthly amounts makes it feel more achievable.
You can also divide your savings into separate categories so that money intended for emergencies is not easily spent on entertainment or other non-essential purchases.
7. Cancel Unnecessary Subscriptions
Subscriptions can quietly drain your income because their payments may be deducted automatically.
Review your recurring expenses, including streaming services, mobile applications, gym memberships, internet packages, and other services you pay for regularly.
Ask yourself whether you use each service enough to justify its cost.
If you have several subscriptions serving the same purpose, consider keeping only the one you use most. You can also downgrade to a less expensive plan or cancel services you no longer need.
For example, cancelling a ₦3,000 monthly subscription saves ₦36,000 over twelve months, provided you do not replace it with another expense.
Small adjustments like this can create extra room in your budget without requiring you to increase your income.
8. Avoid Unnecessary Debt
Borrowing money for non-essential purchases can make saving more difficult, especially when loans come with high interest rates and additional fees.
Before taking a loan, consider whether the expense is necessary and whether you can comfortably afford the repayments.
If you already have debt, create a repayment plan that accounts for minimum payments, interest rates, and your essential living expenses. Depending on your situation, paying down expensive debt may be a higher priority than making additional savings deposits.
Avoid taking new loans simply to maintain a lifestyle you cannot afford.
Using credit responsibly and reducing unnecessary borrowing can free up more money for savings over time.
9. Compare Prices Before Making Purchases
Prices for the same product or service can vary between sellers. Comparing prices before purchasing can help you avoid spending more than necessary.
Before buying groceries, household items, clothing, electronics, or other products, compare prices from different reliable sellers.
However, do not focus on price alone. Consider quality, durability, transportation costs, delivery charges, and the seller’s reputation.
For example, buying a cheaper product that breaks quickly may cost you more in the long run than purchasing a durable alternative.
You can also save money by buying items when you genuinely need them rather than purchasing them simply because they are on sale.
Being a smart shopper means getting good value for your money, not always choosing the cheapest option.
10. Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses, such as medical bills, urgent repairs, temporary loss of income, or other genuine emergencies.
Without emergency savings, you may be forced to borrow money or sell important assets when unexpected situations arise.
Start by saving a small amount regularly. Your first goal could be to accumulate enough money to cover one unexpected expense. Over time, work toward building savings that can cover several months of essential living expenses, depending on your circumstances.
Keep emergency money somewhere safe and accessible, but separate from the account you use for everyday spending.
Remember that an emergency fund is not meant for routine shopping, entertainment, or planned purchases. Its purpose is to provide financial protection when something unexpected happens.
Conclusion
Saving money every month does not require a high income or a complicated financial strategy. It starts with making conscious decisions about how you earn, spend, and manage your money.
By creating a budget, paying yourself first, tracking expenses, reducing impulse purchases, cooking at home, setting savings goals, reviewing subscriptions, managing debt, comparing prices, and building an emergency fund, you can gradually improve your financial situation.
You do not have to implement all ten strategies perfectly from the beginning. Choose two or three that suit your current circumstances and practise them consistently before adding more.
The most important thing is to start, even if you can only save a small amount. Over time, consistent saving can help you prepare for unexpected expenses, achieve important goals, and develop greater confidence in managing your finances.
Start today: Review your spending, identify one expense you can reduce, and set aside a realistic amount for savings this month. Your future financial security can begin with that single decision.
Disclaimer: This article is for general educational purposes and does not constitute personalized financial advice.